Why we built Ziya for the whole loan, not just collections.
23 September 2026 · ZyroAI team
Spend one afternoon on an NBFC ops floor and you'll notice something odd. The collections team has a dialer. Sales has a different dialer. Customer service has an IVR that everyone hates. Verification has two interns and a spreadsheet. Four teams, four tools, and the same borrower talking to all of them. Who, by the way, can tell none of them know each other.
Everyone who pitched us "voice AI" was selling a fifth tool for one of those rooms. Usually collections, because that's the easiest ROI story to tell. We thought that was backwards. So we built Ziya to work the whole loan.
What an AI voice agent for lending actually is
Cut through the jargon: it's software that can hold a phone conversation and then do something about it. Not an IVR — nobody's pressing 1. The borrower talks the way they actually talk ("मेरी EMI kitni hai? aur late fee kyun laga?"), gets an answer, and the system behind the call updates itself. The LMS entry, the promise-to-pay date, the payment link on WhatsApp. If the software can only chat but can't touch your LOS or LMS, it's a toy. That's the whole test.
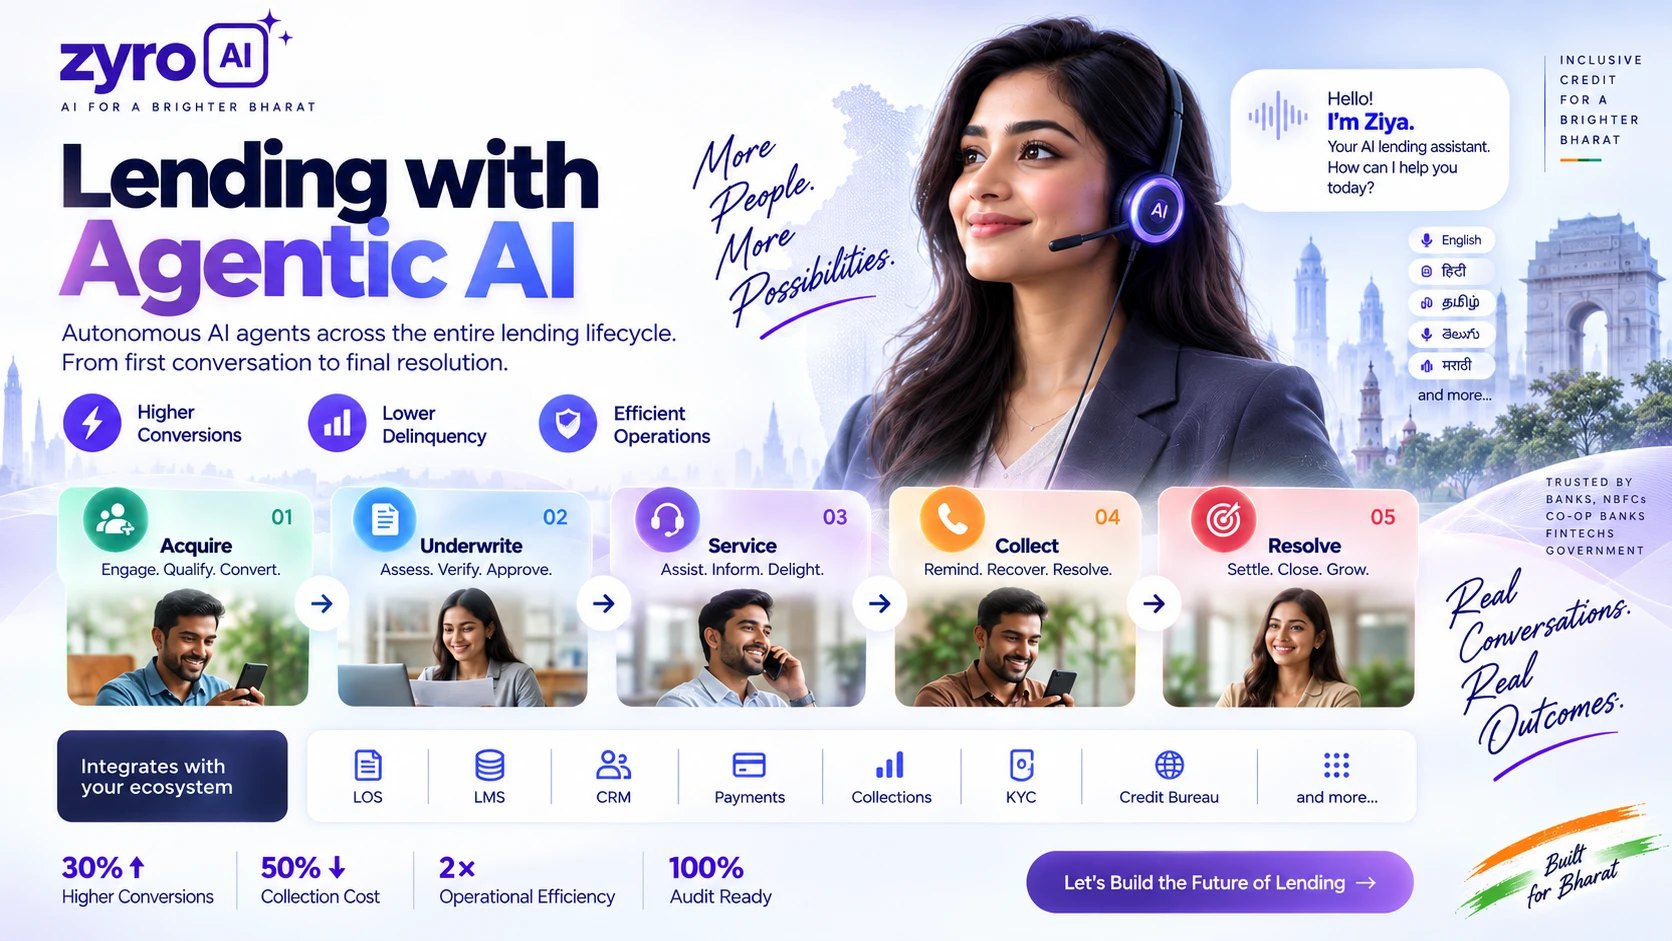
The same agent, five different jobs
A loan has a life. Somebody enquires, somebody underwrites, somebody asks where their statement is, somebody forgets an EMI, somebody disputes a charge. Today a different team (and vendor) owns each of those calls. Ziya's design bet is that one agent should follow the borrower through all of it.
At the top of the funnel, speed is basically everything. A loan lead that waits until tomorrow morning is someone else's customer tonight. Ziya calls back in seconds and asks the boring-but-necessary questions (salaried or self-employed, which product, how much) so a human picks up a warm file, not a cold number.
In underwriting, nothing dies of rejection; files die of waiting. "PAN aa gaya, bank statement nahi aaya." Someone has to chase that, and that someone is expensive. Chasing is exactly what a machine should do — politely, thrice if needed, in the borrower's language, and paired with our Digital KYC flow so the document lands in the file, not in a WhatsApp forward.
Service is the unglamorous middle. Balance, due date, foreclosure charge, "statement bhej do." These calls are why your support queue exists and why nobody answers them at 9pm. An agent answers at 9pm. And 2am. Escalates the genuinely messy ones to a human, with the transcript attached so the borrower doesn't repeat the story a third time.
Collections is where every voice-AI vendor starts, and fair enough. It works there. EMI reminders before due date, early-bucket outreach, capturing the reason and the promise. The part people underrate: the machine actually calls back on the promised date. Humans forget; that's not a criticism, it's a Tuesday. We wrote a separate, longer piece on this: AI voice agents for collections in India.
And resolution — disputes, reversals, the angry call. The agent's job here is honestly modest: acknowledge instantly, log it properly, escalate with context. Most "servicing anger" is really "nobody picked up" anger.
The part vendors don't love to discuss
Compliance. RBI's fair-practice expectations are not optional decoration. Calling hours, respectful language, saying accurately what is owed. Here the machine has an unfair advantage, and we should be honest that it's an advantage of boringness: it reads the approved script every single time, and every call leaves a transcript. Pair that with Speech Analytics and your QA coverage goes from "we sampled 2% last quarter" to every call, flagged the same day. Ask your current BPO what their sampling rate is. Then ask when the last audit finding surfaced.
Hindi-English is one language, not two
Our test for any voice system, including our own: "मेरी EMI कितनी है, and can you send the link?" One sentence, two scripts. If the bot asks the borrower to "please repeat in English," it has already failed in Bharat. Ziya was built for code-switching first because that's how the country actually talks — Hindi, English, Tamil, Telugu, Marathi, Bengali, and the mixtures in between.
Don't take our word — call her
We keep a public demo running because slides are easy and calls are not. Open it, pick a borrower persona, hit the green button, ask her about the EMI: learn.myzyro.com. The transcript scrolls live while you talk. If it impresses you, book a walkthrough and we'll run it on your call flows instead of our sample ones.
Questions we keep getting
Does this replace my calling team?
No, and anyone who says yes is selling too hard. It takes the routine bulk (reminders, status, qualification) and hands your people the calls that need judgement. The escalation arrives with the transcript, which your team will appreciate more than the automation itself.
Which systems does it plug into?
LOS, LMS, CRM, payment links, collections stack, KYC and bureau checks. Over APIs, scoped during onboarding. Sandbox access on request from the product pages.
Which languages?
22+ Indian languages, and (more importantly) the mixed speech between them.
Is it compliant for collections calling?
Configured calling hours, approved scripts, full transcripts and audit trail; India-hosted or on-premise. Longer answer on the security page.
Related: why 2% call sampling fails · Voice AI product page